
Offset Account Errors Are Costing Borrowers Millions
An offset account is designed to help reduce the interest you pay on your home loan. But a major review by the Australian Securities and Investments Commission (ASIC) has found some borrowers haven’t been receiving the savings they expected.
ASIC reviewed eight banks representing more than 70% of Australia’s $2.5 trillion home loan market and identified weaknesses in the way all eight banks set up, monitored and managed mortgage offset accounts.
Reports made to ASIC between 1 September 2023 and 31 August 2025 show banks paid more than $55 million in compensation for offset account failures. ASIC expects that figure to increase as banks continue reviewing and remediating affected customers.
For homeowners with an offset account, the message is simple: don’t automatically assume your offset is working as intended.
What Did ASIC Find?
ASIC’s review identified several weaknesses in the way mortgage offset accounts were being handled.
Some banks struggled to readily identify whether customers had requested an offset account. ASIC also found inconsistent detection of offset failures, delays in fixing problems and compensating customers, and limited visibility for customers trying to determine whether their offset was working correctly.
ASIC reviewed data relating to 204,000 unique home loans settled between March and August 2025.
Among the offset failures identified by banks in that data:
- 55% involved an offset account that had been opened but wasn’t linked.
- 22% involved an offset account that hadn’t been opened.
- 14% involved an account that wasn’t linked within the time frame communicated to the customer.
- 9% involved other failures.
That first figure is particularly important. You can have an offset account sitting there with money in it, but if it isn’t correctly linked to your mortgage, it may not be reducing your home loan interest.
Why Can an Offset Account Error Be Hard to Spot?
This is where things get sneaky.
When an offset account isn’t working properly, your required mortgage repayment may remain exactly the same.
Instead, more of your repayment can go towards interest and less towards reducing your principal. Over time, that can mean paying considerably more interest and potentially taking longer to repay your home loan.
ASIC provided a hypothetical example involving a $750,000 home loan and an average offset balance of $50,000. If the offset wasn’t linked correctly, the borrowers could pay more than $3,000 in additional interest in just one year.
How Should an Offset Account Work?
A mortgage offset account is a transaction account linked to your home loan.
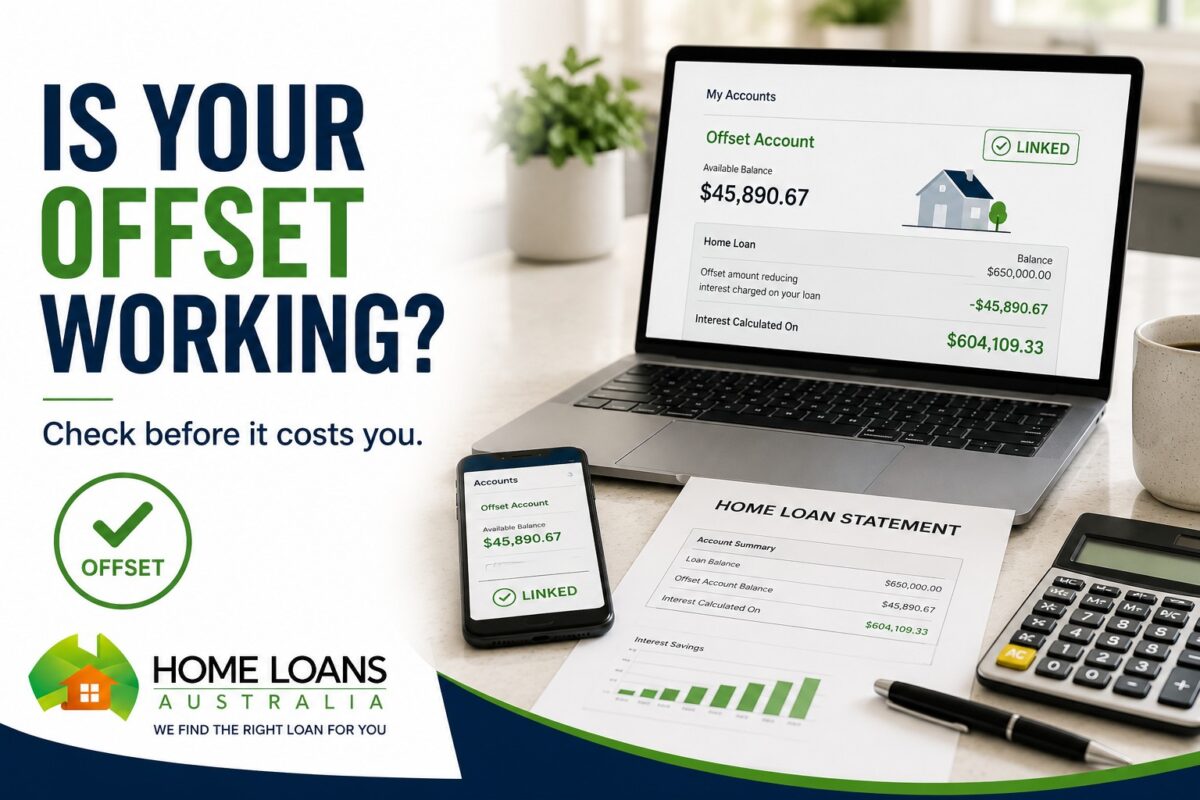
The balance held in the account is used to reduce the portion of your mortgage on which interest is calculated.
For example, if you had:
Home loan balance: $700,000
Offset account balance: $40,000
You would generally be charged home loan interest on $660,000, rather than the full $700,000.
Your required repayment may remain unchanged, but because you’re paying less interest, more of that repayment can go towards reducing the loan principal.
Over time, a correctly used offset account can potentially reduce both the interest you pay and the time it takes to repay your mortgage.
How to Check Your Offset Account Is Working
ASIC is encouraging borrowers with mortgage offset accounts to check that they’re actually receiving the benefit they’re expecting.
There are three particularly important things to check:
- Make sure the offset account has actually been set up.
- Confirm it’s linked to the correct home loan.
- Check that you’re receiving the expected interest-saving benefit.
Start with your lender’s mobile app, online banking or home loan statements.
If you can’t clearly see how your offset is linked or whether you’re receiving the benefit, contact your lender and ask them to confirm it.
Recently Refinanced or Changed Your Loan? Check Again
This is one I’d highlight for Home Loans Australia clients.
ASIC specifically warns that changes such as refinancing or switching home loan products can result in an offset account becoming disconnected from the loan. In some circumstances, borrowers may need to ask their lender to re-link it.
So even if your offset worked perfectly when you originally established the mortgage, it’s worth checking again after making changes to your home loan.
Is an Offset Account Always Worth Having?
Not necessarily.
An offset account can be extremely useful, particularly if you maintain a reasonable cash balance. However, some offset-enabled home loans can come with higher interest rates, package fees or account fees.
The important question isn’t simply “Do I have an offset?”
It’s “Is my offset saving me more than it’s costing me?”
That means considering your average offset balance, home loan interest rate, fees and alternative loan options.
Could Your Home Loan Structure Be Working Harder?
Australians held approximately $349.1 billion in mortgage offset accounts as at March 2026, up 28% over two years. With that much money sitting in offsets, making sure those accounts are operating correctly matters.
If you haven’t checked your offset recently, now is a good time.
At Home Loans Australia, we can help you understand how your home loan and offset account are structured, review whether your loan remains competitive and explain what to ask your lender if something doesn’t look right.
Your offset is there to save you interest. It’s worth making sure it actually is.
Frequently Asked Questions
What is a mortgage offset account?
A mortgage offset account is a transaction account linked to your home loan. Money held in the account reduces the portion of your mortgage used to calculate interest.
How do I know if my offset account is working?
Check your online banking, lender app or statements to confirm the account is linked to the correct home loan and that you’re receiving the expected interest benefit. If it isn’t clear, ASIC recommends contacting your lender.
Can an offset account be open but not linked to my mortgage?
Yes. ASIC found this was the most common type of offset failure identified in the data supplied by the reviewed banks, accounting for 55% of identified failures.
Can refinancing affect my offset account?
Yes. ASIC says refinancing or switching home loan products can result in an offset account becoming disconnected, so borrowers should check their offset following changes to their loan.
How much have banks paid for offset account errors?
Reports to ASIC between September 2023 and August 2025 show banks paid more than $55 million in compensation, with further compensation expected.
