
How to Pay Off Your Mortgage Faster: 5 Simple Strategies
Learning how to pay off your mortgage faster could potentially save you thousands of dollars in interest and help you become mortgage-free years earlier.
But with higher living costs and elevated interest rates putting pressure on household budgets, finding hundreds or thousands of dollars for large additional repayments isn’t realistic for everyone.
The good news is that getting ahead on your home loan doesn’t necessarily require dramatic changes.
Small adjustments to the way you manage your mortgage can add up over time.
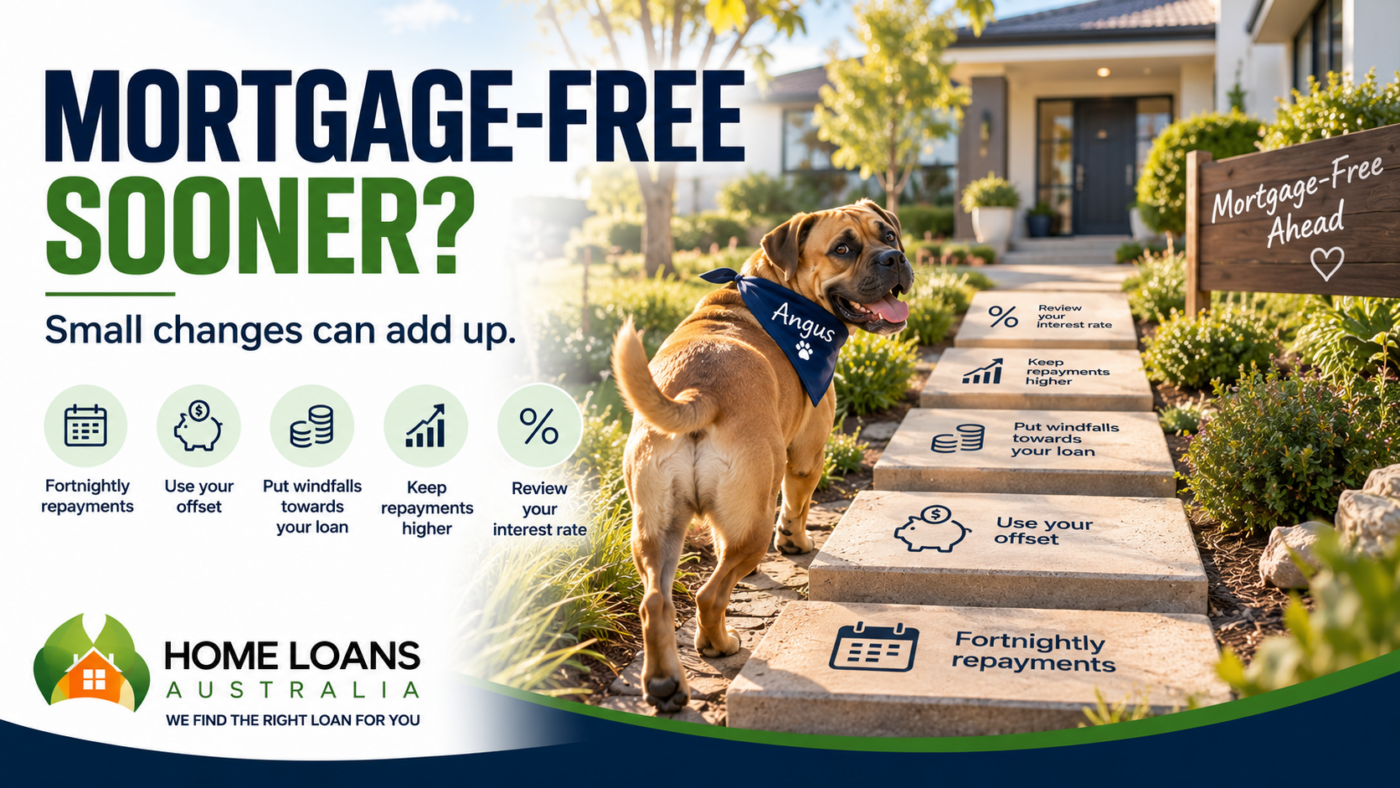
Here are five strategies worth considering.
1. Consider Making Fortnightly Mortgage Repayments
One relatively simple strategy is to look at how frequently you make your home loan repayments.
If you currently make monthly repayments, you could consider paying half your monthly repayment every fortnight.
Why can this make a difference?
There are 12 months in a year, but 26 fortnights. Paying half your monthly amount 26 times can therefore result in the equivalent of 13 monthly repayments rather than 12 over a year.
That additional repayment can help reduce your principal, which may reduce the amount of interest you pay over the life of the loan.
However, lenders can calculate repayment frequencies differently, so check how your particular lender treats fortnightly repayments before making changes.
2. Use Your Offset Account Strategically
If your home loan has an offset account, keeping spare cash in it can be another way to potentially reduce home loan interest.
An offset account is linked to your mortgage, with the balance generally reducing the portion of your home loan on which interest is calculated.
For example, if your mortgage balance was $600,000 and you maintained $30,000 in a 100% offset account, interest would generally be calculated on $570,000 rather than $600,000.
That means money you might otherwise keep in an everyday transaction or savings account could potentially be working to reduce your mortgage interest.
You still retain access to the money, which can make an offset particularly useful for maintaining an emergency or financial buffer.
It’s important to make sure your offset account is correctly linked and to compare any fees or higher rates associated with an offset-enabled loan.
3. Put Unexpected Money Towards Your Mortgage
Not every extra repayment needs to come from your regular household budget.
Occasional windfalls could provide an opportunity to reduce your home loan principal without changing your everyday spending.
This might include a tax refund, work bonus, inheritance or another unexpected lump sum.
You don’t necessarily need to put the entire amount towards your mortgage either.
For example, you might decide to keep part of a tax refund for your savings buffer and direct another portion towards your home loan.
The important part is that additional repayments made earlier in the life of a mortgage can have more time to reduce the interest you would otherwise pay.
Before making lump-sum repayments, check whether your loan has restrictions or fees for additional repayments, particularly if you have a fixed-rate home loan.
4. If Interest Rates Fall, Consider Keeping Your Repayments Higher
If interest rates eventually fall and your minimum home loan repayment decreases, there’s another strategy you could consider.
Keep paying the higher amount.
Rather than absorbing the difference back into your household spending, continuing with your previous repayment amount means the additional money may go towards reducing your mortgage faster.
Because you’ve already adjusted your household budget to the higher repayment, it can be a relatively painless way to accelerate your progress.
Of course, everyone’s circumstances are different. If your household budget needs some breathing room, reducing your repayment may be entirely appropriate.
The key is knowing you have the choice.
5. Review Your Home Loan Interest Rate
Sometimes getting ahead isn’t about finding more money.
It’s about paying less interest on the money you’ve already borrowed.
Home loan rates and lender offers change over time. If you’ve had the same mortgage for several years, your current interest rate may no longer be as competitive as it once was.
A home loan review can help you compare your existing loan with other options.
Depending on your circumstances, refinancing to a more competitive rate could reduce the interest you pay.
You could then choose to pocket the saving or, if your budget allows, continue making the same repayment and direct the difference towards reducing your mortgage faster.
Can Small Extra Mortgage Repayments Really Make a Difference?
Yes. Small additional repayments can potentially have a significant cumulative effect over a long home loan term.
That’s because home loan interest is generally calculated on the outstanding loan balance.
Every additional dollar that reduces your principal may also reduce the balance on which future interest is calculated.
You don’t necessarily need to find a huge lump sum.
An extra amount each fortnight, money left sitting in an offset account or an occasional lump-sum repayment can all contribute towards reducing the principal over time.
Don’t Forget Your Financial Buffer
There’s an important caveat to any strategy designed to pay off your mortgage faster.
Throwing every available dollar at your home loan isn’t necessarily the best approach.
Unexpected expenses happen. Cars need repairs, appliances retire spectacularly without giving notice, and household expenses don’t always consult your spreadsheet first.
Maintaining an appropriate emergency or cash buffer can help you manage unexpected costs without needing to rely on credit.
If you use an offset account, your emergency savings may potentially perform both jobs: remaining accessible while also reducing the balance used to calculate home loan interest.
Check Your Loan Conditions Before Making Extra Repayments
Before changing your repayment strategy, check the conditions of your home loan.
Variable-rate loans commonly provide flexibility around additional repayments, but conditions vary between lenders.
Fixed-rate home loans can be more restrictive. Some lenders limit how much extra you can repay during the fixed period, and exceeding those limits could result in fees or break costs.
It’s worth understanding exactly how your loan works before changing your repayment pattern or making a significant lump-sum payment.
Is Your Home Loan Helping You Get Ahead?
If your goal is to become mortgage-free sooner, your interest rate is only one piece of the puzzle.
Your repayment frequency, offset account, loan features, additional repayment rules and overall loan structure can all influence how quickly you make progress.
At Home Loans Australia, we can review your current mortgage, compare available options and help you understand whether your rate, loan features or repayment setup could help you pay off your mortgage faster. Contact us now to discuss your options: https://homeloansoz.com.au/contact/
Sometimes getting ahead doesn’t require one enormous financial leap.
A few small moves, repeated consistently, can do a surprising amount of heavy lifting.
Frequently Asked Questions About Paying Off Your Mortgage Faster
What is the fastest way to pay off a mortgage?
There isn’t one strategy that suits everyone. Making additional repayments, using an offset account effectively, reviewing your interest rate and directing occasional lump sums towards the principal may all help reduce a mortgage sooner.
Is it better to pay a mortgage weekly, fortnightly or monthly?
It depends on how the lender calculates repayments. Paying half your normal monthly repayment every fortnight can result in 26 half-payments each year, equivalent to 13 monthly amounts. Check with your lender because repayment calculations vary.
Does an offset account help pay off a mortgage faster?
A correctly linked 100% offset account can reduce the loan balance used to calculate interest. If your repayments remain unchanged, reducing interest can allow more of your repayment to contribute towards reducing principal.
Should I put my tax refund into my mortgage?
Putting some or all of a tax refund towards your mortgage can reduce the outstanding principal. However, consider your other financial commitments and maintain an appropriate emergency cash buffer.
Should I keep my mortgage repayments the same if interest rates fall?
If your lender reduces your required repayment following an interest rate cut, continuing to pay the previous higher amount may help reduce your principal faster. Whether this is appropriate depends on your financial circumstances and loan conditions.
Is it better to make extra repayments or keep money in an offset?
Both can reduce the effective balance on which interest is calculated, depending on the loan. An offset can provide greater access to your money, while an additional repayment may be subject to redraw rules. Compare the features and conditions of your particular loan.
